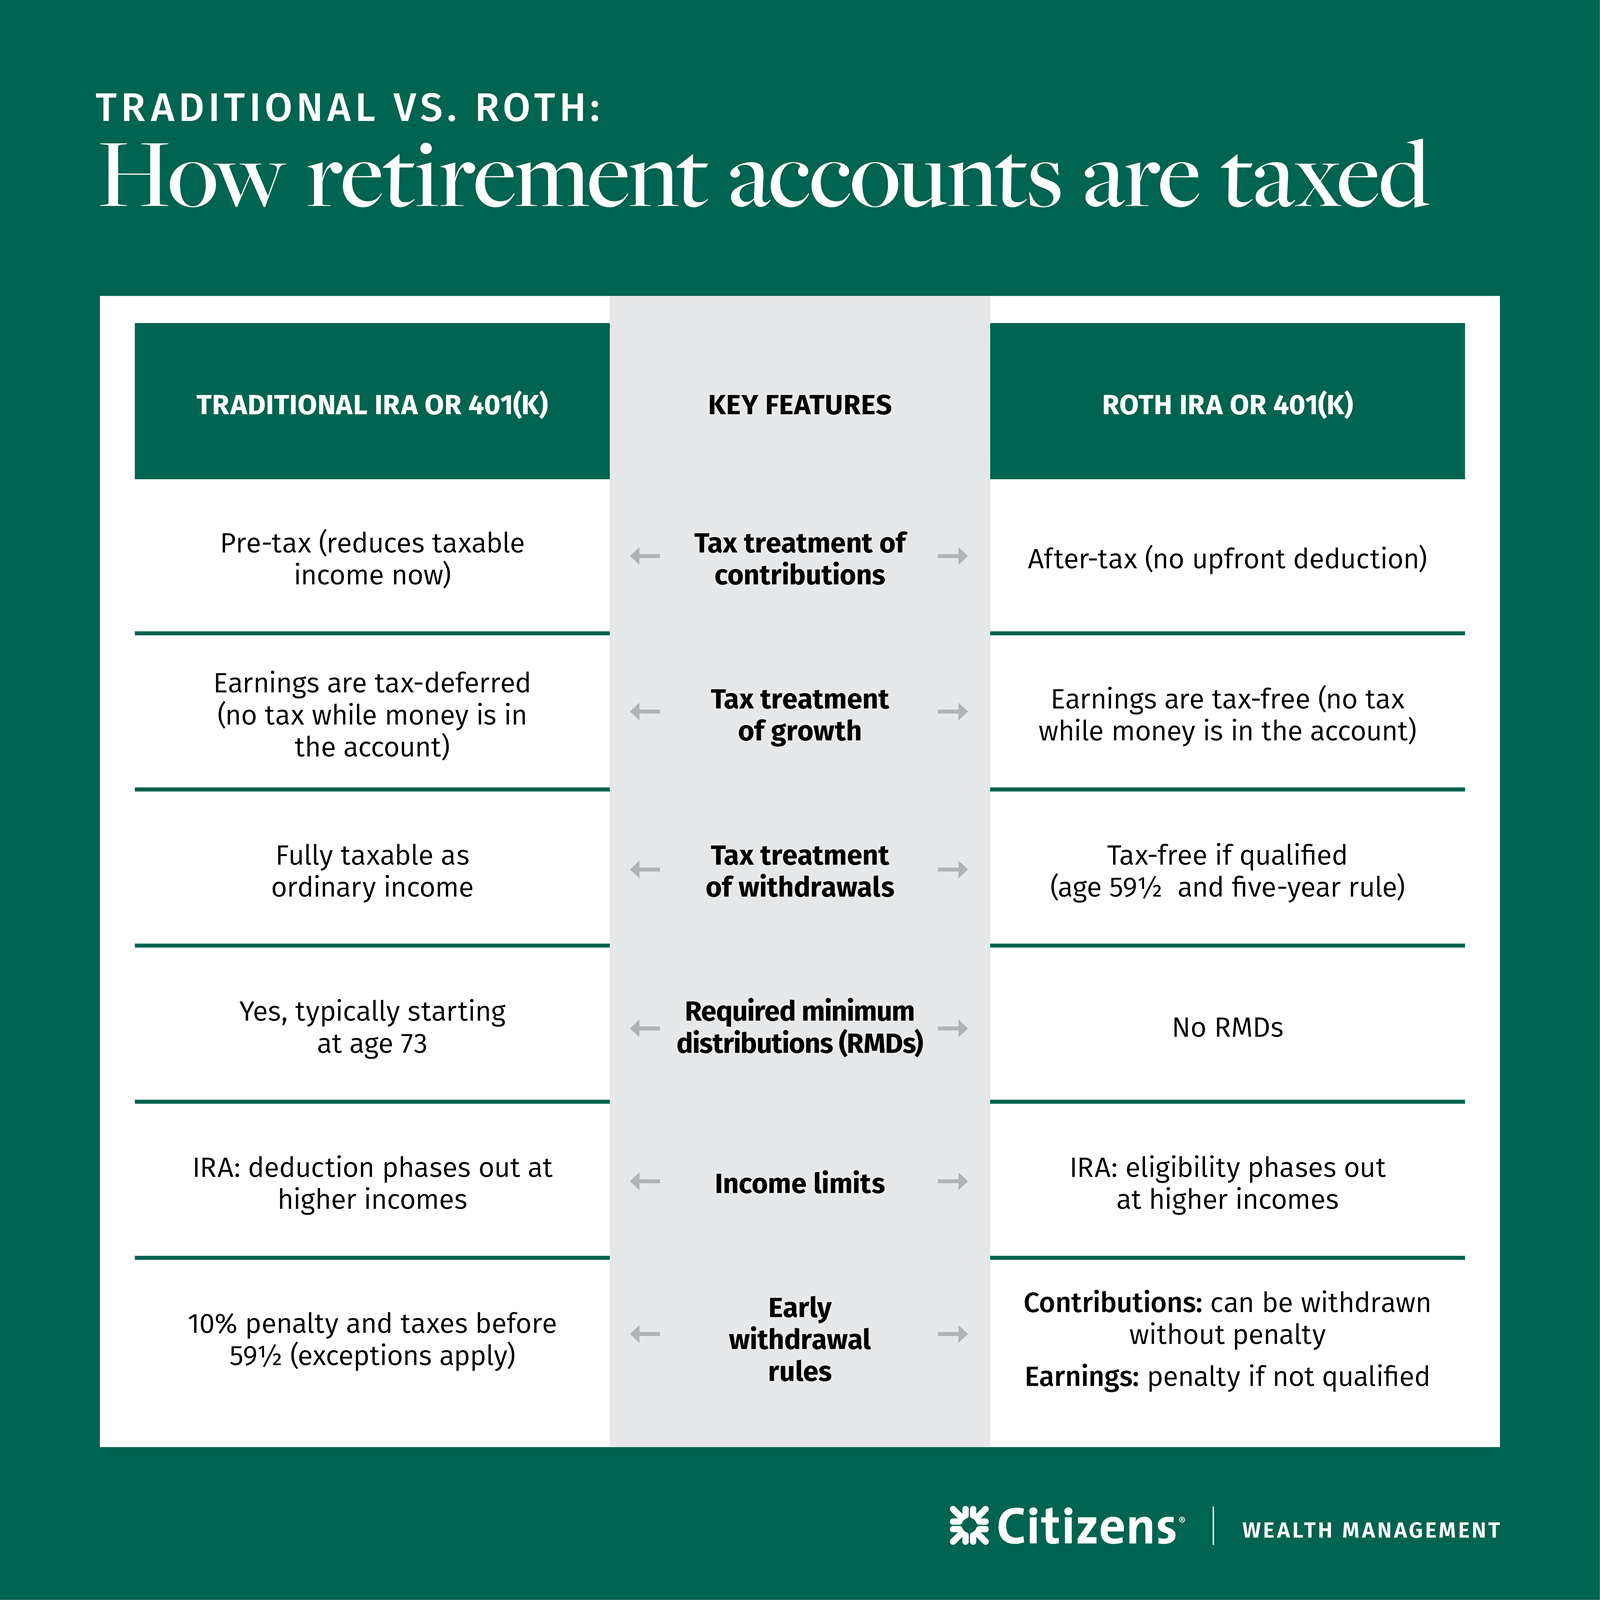

When I first started looking into retirement savings, I was immediately overwhelmed by the number of options available. One question that kept coming up was, “Is a Traditional IRA the same as a Simple IRA?” It’s a common confusion, and honestly, the names don’t make it any easier. Both are retirement accounts, but they’re designed for different purposes and come with distinct rules. In my experience, understanding these differences is crucial to making the right choice for your financial future.
What Are Traditional and Simple IRAs?
Let’s start with the basics. A Traditional IRA is an individual retirement account that allows you to save for retirement with tax-deferred growth. Contributions may be tax-deductible, depending on your income and whether you’re covered by a workplace retirement plan. On the other hand, a Simple IRA (Savings Incentive Match Plan for Employees) is an employer-sponsored retirement plan designed for small businesses. It combines elements of a 401(k) and a Traditional IRA but with simpler administrative requirements.
Key Differences Between Traditional and Simple IRAs
To make it clearer, here’s a side-by-side comparison of the two:
| Feature | Traditional IRA | Simple IRA |
|---|---|---|
| Eligibility | Anyone with earned income | Employees of companies offering Simple IRA plans |
| Contribution Limits (2023) | $6,500 ($7,500 if age 50+) | $15,500 ($19,000 if age 50+) |
| Employer Involvement | None | Required; must match contributions (up to 3% of employee’s salary) |
| Tax Deductibility | May be deductible, depending on income and workplace plan coverage | Contributions are always tax-deductible |
| Withdrawal Rules | Penalties for withdrawals before age 59½ (unless an exception applies) | Penalties for withdrawals before age 59½, with an additional 25% penalty if withdrawn within the first 2 years of participation |
Eligibility and Setup
One of the most significant differences is who can use these accounts. A Traditional IRA is open to anyone with earned income, making it a flexible option for self-employed individuals or those without access to an employer-sponsored plan. In contrast, a Simple IRA is only available to employees of companies that offer this specific plan. If your employer doesn’t provide it, you’re out of luck.
Contribution Limits
Contribution limits are another area where these accounts diverge. For 2023, the maximum contribution to a Traditional IRA is 6,500 (7,500 if you’re 50 or older). A Simple IRA allows for much higher contributions, up to 15,500 (19,000 if you’re 50 or older). This makes the Simple IRA a more attractive option for those looking to save aggressively for retirement.
💡 Note: If you’re self-employed, consider a SEP IRA or Solo 401(k) instead, as they often allow for higher contributions than a Traditional IRA.
Employer Involvement
Here’s where the Simple IRA really stands out. Employers are required to contribute to their employees’ Simple IRAs, either through a matching contribution (up to 3% of the employee’s salary) or a non-elective contribution of 2% of compensation. This employer match can significantly boost your retirement savings, something a Traditional IRA doesn’t offer.
Tax Implications
Both accounts offer tax-deferred growth, meaning you don’t pay taxes on the earnings until you withdraw the funds in retirement. However, the tax deductibility of contributions differs. With a Traditional IRA, your contributions may be tax-deductible, depending on your income and whether you’re covered by a workplace retirement plan. Simple IRA contributions, on the other hand, are always tax-deductible.
Withdrawal Rules
Both accounts impose penalties for early withdrawals before age 59½, but the Simple IRA has an additional wrinkle. If you withdraw funds within the first two years of participating in the plan, you’ll face a hefty 25% penalty on top of the standard 10% early withdrawal penalty. This makes the Simple IRA less flexible for those who might need access to their funds sooner.
Who Should Choose Which?
Deciding between a Traditional IRA and a Simple IRA depends on your situation. If you’re self-employed or your employer doesn’t offer a Simple IRA, a Traditional IRA is a solid choice. It’s also a good option if you want more control over your investments, as you can open a Traditional IRA with most financial institutions.
On the other hand, if your employer offers a Simple IRA, it’s hard to ignore the benefits of the employer match. Even if you’re only contributing enough to get the full match, you’re essentially getting free money toward your retirement. Plus, the higher contribution limits make it a better option for those looking to maximize their savings.
⚠️ Note: Always consider your tax situation when choosing between these accounts. If you expect to be in a lower tax bracket in retirement, a Traditional IRA or Simple IRA might be more advantageous due to tax-deferred growth.
In my experience, the choice often comes down to accessibility and employer involvement. If you have the option, a Simple IRA can be a powerful tool for building retirement savings, especially with the employer match. But if you’re on your own, a Traditional IRA is a reliable and flexible alternative.
Understanding the differences between these accounts is the first step toward making an informed decision. Whether you go with a Traditional IRA or a Simple IRA, the most important thing is to start saving for retirement now. The earlier you begin, the more time your money has to grow, and that’s a principle that applies no matter which account you choose.
Related Terms:
- rules of a simple ira
- simple ira vs regular
- simple ira and traditional contributions